XIAM007

Making Unique Observations in a Very Cluttered World

Saturday, 29 August 2009

Gold Is Pale Because It Has So Many Thieves Plotting Against It

Reading - Gold Is Pale Because It Has So Many Thieves Plotting Against It http://bit.ly/qyYdO

The title is a quotation from Diogenes Laertius (fl. 2nd century A.D.) This was the favorite quotation of the late Chicago economist and gold expert Melchior Palyi.

25 years ago I visited Comex at the World Trade Center, watching the feverish activity in the gold pit from behind the glass wall in the gallery. A gentleman standing next, unknown to me, remarked: "One day this make-believe charade will come to a bad end. All that these guys are doing down there is creating ever more claims to the same lump of gold -- just as governments have been doing before they met their ignominious fate."

Later that day I went to see the Director of Research of Comex. During our chat that lasted about an hour he intimated that he was greatly disturbed by the mystery that the gold basis has been steadily declining year in and year out. Perhaps it was the fact that he could not solve the puzzle that bothered him so much that he quit his job a few months later.

I must confess that I could not solve that puzzle myself until the Twin Towers of the World Trade Center came tumbling down many years later. For me it was a symbolic event, conjuring up the unknown gentleman and bringing back his cryptic remark. We are watching a game of musical chairs. When the music stops, paper claims to gold will be dishonored, and the gold futures markets will tumble down just like the Twin Towers.

In my earlier article The Dress Rehearsal for the Last Contango I observed that "a very strange phenomenon has been manifesting itself during the past thirty-five years, since the inception of gold futures trading. The basis as a percentage of the rate of interest, rather than remaining constant, has been vanishing and, by now, it has dropped to zero." In the rest of that article I drew

attention to the apocalyptic consequences of the prospect of permanent backwardation in gold threatening the world, which is completely ignored by the makers of monetary policy, as I had opportunity to convince myself during my recent encounter with Paul Volcker, the Chairman of President Obama's Economic Recovery Advisory Board. As I see it, the Debt Tower will topple, just as the Twin Towers of the World Trade center have, when hit by permanent gold backwardation. The reason is that the availability of gold is absolutely indispensable for maintaining our system of irredeemable debt. Only then will bondholders, like the participants of the game of musical chairs, be satisfied that there is a goodly number of vacant chairs available, so let's get on with bond trading, gold futures trading, and let the music roar on.

But once permanent backwardation in gold establishes itself, gold is no longer available at any price. Bondholders will scramble to sell their irredeemable bonds before they lose all their remaining value. There is no other way to pacify bondholders than letting the game of musical chairs go on, that is, continue the charade of gold futures trading putting ever more claims on the same lump of gold.

The response to my article was overwhelming. I have never realized how many people out there are following my writings on the internet so closely. I want to thank every one of you and assure you that I take this responsibility most seriously. Even if I cannot answer every message I get from you individually, I will continue to do my best to explain the results of my research in simple, understandable terms.

Let me spell out for my readers what the vanishing of the gold basis means from the point of view of the puppet-masters of the gold futures markets. It means that they are fighting a losing battle. They are desperately trying to coax gold out of hiding by offering ever higher bribes -- not in terms of the price but in terms of the basis. A low basis means that they offer to take your cash gold and let you have gold futures in exchange at a discount price. (The discount is contango minus the basis, so that the two are inversely related: as the basis falls, the discount increases.) This will allow you to invest an amount equal to the price of gold (less five percent, the margin on the gold future) in any way you want and, having paid the reduced contango, you can keep the profits. The point is that you will still benefit from any advance in the gold price, same as you would if you owned cash gold. You can have your cake and eat it.Remember, in a full carrying charge market, such as the gold futures markets were at inception, no such bribe money was offered.

But, lo and behold, people who are willing to take the bribe are few and far in between. So the pot is sweetened. The basis is lowered. Maybe at one point gold will be coaxed out of hiding, once the bribe is high enough.

No such luck. When the basis gets as low as zero, it means that the discount on gold futures has gone so high that it is equal to the opportunity cost of holding gold. Therefore, again, if you give up your cash gold in exchange for gold futures, you can invest an amount equal to the price of gold (less five percent) in any way you wish, but now they let you keep your profit in its entirety. Andyou can still benefit from any advance in the gold price, same as you would if you had the cash gold in your hands.

This is where we are now. Indications are that the game fish still does not bite. What now? Where do the futures markets in gold go from here? Well, the pot can be further sweetened. The basis can be pushed down into negative territory. Gold could be forced into backwardation. Let's see what that means. It means that you can sell cash gold andbuy it back for future delivery at an outright discount. Somebody wants your gold so badly that he is willing to pay you for the privilege of holding it for a few days, few weeks, few months paying your storage and insurance fees. You get your gold back at a cheaper price. You make a risk-free profit on this deal. If the gold price goes up in the meantime, you benefit fully, just as if you have held on to the cash gold.

Now risk-free profits are a promise of unlimited profits because, if you are nimble enough, then you can make any number of round trips. However, opportunities to earn risk-free profits from arbitrage do not last. Other nimble speculators would jump in and their unlimited action would close the spread that gave rise to the risk-free profit in the first place. Yet I predict that, after a period of initial vacillation between backwardation and contango (due to action by misinformed traders) gold will settle in permanent backwardation.

Wouldn't that be loverly? Risk-free profits galore. No need to bother with storage charges and insurance premiums. Just sit back and enjoy the ride to riches.

But hey, wait a minute! Is the arbitrage really risk-free? You give up your cash gold, but what if your gold futures contract expires and they refuse to return your gold? Commodity markets can change the rules of the game mid-stream. They just declare 'cash settlement only' for outstanding contracts. Unsaid and unstated, not even mentioned in small print, is the fact that the trap door may be slammed shut. The investor who has taken the bribe is neatly separated from his gold when the hairy godfather waves his magic wand. "Gold is pale because it has so many thieves plotting against it." There are all too many trap doors, sprung wide open, ready to devour gold belonging to the unweary.

That's it. That's why more people do not fall for the bribe even when tickled with promises of risk-free profits. The promise is mendacious. There is a risk: the risk that you lose your gold and you may never be able to buy it back at any price. There is no other explanation for the fact that the promise of risk free profits does not eliminate the discount on the futures price of gold. This is the true explanation for the coming permanent backwardation in gold.

Gold futures trading is clearly a con-game, but it is in a symbiotic relation with the regime of irredeemable currency and irredeemable debt, on which our 'democracy' is based. So we have a double con-game. We have a smaller con-game of gold future trading inflicted upon gullible people who want to have their cake and eat it and, then, we have the much bigger, all-embracing con-game of irredeemable currency, inflicted upon the rest of us, innocent bystanders. It is inflicted by the United States government that stoops so low as to trample on the Constitution mandating a metallic monetary system for this country precisely in order to outlaw all Ponzi-schemes. The government could never muster the moral courage to propose an Amendment that would make the Constitution conform to its monetary system -- as it would open Pandora's box. Rather, it would live with the onus of being in contempt of the Constitution. The government of the United States had looted gold from its own subjects in 1933. It looted even more gold from people not under its jurisdiction in 1971. It continues to operate in the same tradition.

The larger con-game of the irredeemable dollar could not have gone on so long, but for the smaller con-game of gold futures trading from which it takes its strength. Historically, every regime of irredeemable currency has met its Nemesis in no more than 18 years. The present experiment with irredeemable currency has been going on for twice that long. Of course, gold futures trading is a relatively new invention that was not available to the managers of the assignats, mandats, or the Reichsmarks. Nor was it available to the managers of the most recent experiment with the Zimbabwe dollar. But, as the relentless fall in the gold basis clearly shows, people cannot be conned forever. The clock is ticking. Sand in the hourglass keeps dropping. When it runs out, the present experiment with fiat dollar will also meet its Nemesis, as all the earlier experiments have. That's the good news.

The bad news is that the government of the United States persists in continuing the double con-game and Ponzi-scheme through thick and thin. It is callous to the economic damage it is causing world-wide, and it disregards the danger of permanent gold backwardation that would inflict utter economic pain on the innocent people of this country, to say nothing of the people of the rest of the world. As explained above, it would make the runaway debt-tower of Babel topple, burying people under the rubble as the Twin Towers of the World Trade Center buried people working inside.

When that happens, the government of the United States will not have the excuse that it has not been warned. I have delivered the message in person to the Chairman of President Obama's Economic Recovery Advisory Board, Paul Volcker, when we met at the Santa Colomba Conference last July. I also consider it my moral duty to warn all the people who are willing to listen of the danger lying ahead. It is incredibly naïve to believe that gold can be removed from the international monetary system with impunity at the stroke of a pen, as they pretended to do it in 1973. The gold corpse still stirs. When it rises from its prostrate position it will, like Gulliver, dust off the Lilliputians who like ants have been scurrying all over his body. The day of reckoning will have dawned.

Keynesian and Friedmanite economists bear a special responsibility for the disaster. They dug in and monopolized their positions at universities and research institutes. They never allowed a free discussion on the gold standard. They did everything to aggrandize and perpetuate their own power as the sole advisors on government policy. They will not be able to live down this shame in a thousand years.

Masters Gold Fund

In my previous article More Dress Rehearsal of the Last Contango (see References below) I mentioned the unique Masters Gold Fund, soon to come on stream, structured to take advantage of the permanent backwardation in gold when it comes, which would ground all other gold funds. I have acted as advisor from inception and during the incubation period. In that article I listed seven exclusive features spelling out how the Masters Gold Fund would operate in these perilous times. It would take its clues, not from the gold price that is open to manipulation, but from the gold basis which is a pristine indicator telling you about the willingness of gold holders to carry on in playing the game of musical chairs and putting their gold at stake.

Racketeering 101: Bailed Out Banks Threaten Systemic Collapse If Fed Discloses Information

Reading - Racketeering 101: Bailed Out Banks Threaten Systemic Collapse If Fed Discloses Information - http://bit.ly/4j7kAL

And so the guns come out blazing. The Clearing House Association, another name for all the banks that were bailed out over the past year with the generous contributions from all of you, dear taxpayers, are now threatening with anotherinstance of complete systemic collapse if Bloomberg's lawsuit is allowed to proceed unchallenged, let alone if any of the "Audit The Fed" measures are actually implemented.

As a reminder, The Clearing House Association consists of ABN Amro, Bank Of America, The Bank Of New York, Deutsche Bank, HSBC, JP Morgan Chase, US Bank and Wells Fargo.

In a declaration filed in the Bloomberg Case (08-CV-9595, Southern District of New York), the banks demonstrate no shame in attempting to perpetuate the status quo with regard to the Federal Reserve and demand that the wool over the eyes of the general population remain firmly planted in perpetuity.

The Clearing House submits this declaration because the Court's Order threatens to impair the ability of our members to access emergency funds through the New York Fed's Discount Window without suffering the severe competitive harmthat public disclosure of their identity will cause.

Our members have accessed the New York Fed's Discount Window with the understanding that the Fed will not publicly disclose information about their borrowing, especially their identity. Industry experience, including very recent and searing experience, has shown that negative rumors about a bank's financial condition - even completely unfounded rumors - have caused competitive harm, including bank runs and failures.

Surely transparency would facilitate rumor-mongering to an unprecedented degree. After all rumors spread much easier when everyone knows the true financial condition of banks.

And here, in plain written Times New Roman, you see what racketeering by a major bank consortium looks like:

If the names of our member banks who borrow emergency funds are publicly disclosed, the likelihood that a borrowing bank's customers, counterparties and other market participants will draw a negative inference is great. Public speculation that a financial institution is experiencing liquidity shortfalls - which would be a natural inference from having tapped emergency funds - has caused bank customers to withdraw deposits, counterparties to make collateral calls and lenders to accelerate loan repayment or refuse to make new loans. When an institution's customers flee and its credit dries up the institution may suffer severe capital and liquidity strains leaving it in a weakened competitive position.

Pardon me if I am a broken record here, but would rumors not spread much less if there was more transparency, if investors and other financial intermediaries were fully aware of the conditions of their counterparties, if banks did not have to cover their billions in reserve losses by pretending they are viable and essentially being constant wards of the state?

The Banks' racketeering has gone on for far too long.

And yet, it does not stop: the conclusion from the banks' letter:

In sum, our experience differs from the factual conclusions the Court appears to have reached about the nature of competition in the banking industry:

  • The competitive harm to institutions that are publicized as needing emergency funding is not "speculative," but demonstrated by the recent multiple failures of financial institutions whenever information about their funding difficulty has been disclosed.
  • The disclosure does not involve mere "embarassing publicity" but information that could result in the immediate demise of an institution.
  • The disclosure would not merely "stigmatize [ ]"the institution or make it "look [ ] weak," but goes to its very viability.
  • The disclosure of accessing emergency funding is not an "inherent risk" of market participation, but an extraordinary risk in extraordinary circumstances.
  • Competitors can use the disclosure to advertise or publicize that they are financial stronger because they don't need emergency funding.

In a nutshell - the banks want their complete opacity cake and eat it too, or else, the racket goes, the transparency that will somehow promote massive rumor mongering will again destroy capitalism. In the meantime, the Ken Lewises of the world can continue touting how stable their businesses are based on optimistic future projections, while implicitly, they continue to survive merely thanks to the cash granted them by you, taxpayers.

Full filing here:


Clearinghouse_Decl -

AttachmentSize
Clearinghouse_Decl.pdf183.3 KB

Friday, 28 August 2009

Rep. Frank: House will pass Ron Paul’s ‘audit the Fed’ bill this year

Watching - VIDEO - c - http://bit.ly/ztw4P

Powerful House Financial Services Committee chairman says central bank’s lending powers to be ‘curtailed’

Congressman Barney Frank (D-MA), one of the most unabashed liberals in the U.S. House of Representatives, told a Massachusetts town hall recently that Texas Republican Congressman Ron Paul’s bill to audit the Federal Reserve bank will clear his chamber by October.

Over half of the House members, most of them Republican, have signed on to the bill, H.R. 1207.

Though Frank disagrees — as many proponents of the bill contend — that the Fed is the cause of the U.S. dollar’s shrinking value, he told a Massachusetts audience that he’s been a proponent of greater transparency at the nation’s central bank for some time.

“Here’s what we plan to do: I want to restrict the powers of the Federal Reserve in a number of ways,” he said. “First of all, they will be the major losers of power if we’re successful, as I believe we will be, setting up that, uh, financial product protection committee.”

The committee Frank mentioned was proposed by President Barack Obama during the campaign, as a way of protecting consumers. It was formally presented to Congress in the President’s financial regulatory reform white papers in July, noted law firm Wiley Rein LLP.

“The Federal Reserve is now charged with protecting consumers,” continued Frank. “They were supposed to do sub-prime mortgage restricted … Congress in 1994 gave the Federal Reserve the power to adopt rules to ban bad sub-prime mortgages. … They have the power to ban credit card abuses. They have the power to do most of it. They, under Greenspan, did nothing.

“Under Bernanke, they started to do things, but only after Congress started, when I became chairman of the [House Financial Services Committee], we began to act on these things: Sub-prime mortgages, credit cards, overdraft … And after we started, the Fed did. So, that’s why one of the reasons why in the new consumer protection agency we will take away from the Federal Reserve the power to do consumer protection.”

Frank added that Congress will reverse an action by the Democratic Congress of 1932 that gives the Fed authority to lend money at will.

“Under section 13.3 of the Federal Reserve Act, they can lend money to whoever they want,” he said. “We are going to curtail that lending power. We are going to put some constraints on it.”

He concluded: “Finally, we are going to subject them to a complete audit. I’ve been working with Ron Paul, the main sponsor of that bill …” Several in the audience applauded. “He believes that we don’t want to have the audit appear as if it is influencing monetary policy because that would be inflationary … One of the things that will show you is what the Federal Reserve buys and sells. That will be made public, but not instantly. If it were instant, you would have a lot of people trading off that and it would have too much impact on the market. Again, Ron agrees with that. So, we will probably have that data released after a time period of several months — enough time so it won’t be market sensitive.”

Danger in transparency?

The pervasive argument against transparency at the nation’s central banking institution was repeated by Treasury Secretary Tim Geithner during a recent dialog with popular social bookmarking Web site Digg.com.

Geithner said that he’s sure “people understand that you want to keep politics out of monetary policy,” adding that auditing the Fed is “a line that we do not want to cross” because of the possible danger to the U.S. economy.

The argument is strikingly similar to one posed by the Federal Reserve’s legal counsel ina Freedom of Information Act lawsuit filed by Bloomberg News in an attempt to force disclosure of the institutions that received billions in bailout money.

Loretta Preska, chief judge of the Manhattan U.S. District Court, ruled Monday that the Fed had “improperly withheld agency records” in response to the FOIA request, adding that the argument of danger to the economy was based merely on “conjecture” and not evidence.

“[The] risk of looking weak to competitors and shareholders is an inherent risk of market participation; information tending to increase that risk does not make the information privileged or confidential,” she wrote.

Opposition to Fed powers growing

Eliot Spitzer, the disgraced former Governor and Attorney General of New York — at one time known as the “sheriff” of Wall Street — has assaulted the bank bailouts as “America’s greatest theft and cover-up ever” and called the Federal Reserve bank a “Ponzi scheme” that must be held accountable for its actions.

Additionally, the House Domestic Policy Subcommittee plans to probe how the Troubled Asset Relief Program’s (TARP) funds were dispersed by the Fed. Expressing his frustration before the Government and Oversight Committee, Congressman Dennis Kucinich (D-OH) suggested that the Federal Reserve may be paying banks to hoard money and avoid making loans, instead of using the TARP funds to keep people in their homes.

To support his assertion, Kucinich cited a Bloomberg report which noted that “banks’ excess reserves at the Fed rose to a record $877.1 billion daily average in the two weeks ended May 20, from $2 billion a year earlier.

“Excess reserves — money available for lending that banks choose to leave with the Fed instead — averaged $743.9 billion in the first two weeks of this month,” the report continued.

“First, Congress was told that TARP was for the purchase of toxic assets, to help keep people in their homes,” the Congressman said. “Then the Bush Administration switched the program. Next, Congress was told that the TARP funds were instead needed to bail out the banks, in the form of a direct capital infusion, to keep credit markets alive.”

In a media advisory, Kucinich added: “If TARP isn’t about keeping people in their homes or providing credit to businesses, what is it for? I think the vast majority of Americans would be outraged to learn their tax dollars were facilitating hoarding at the Fed and increased profit making for banks.”

Kucinich’s Domestic Policy Subcommittee has also undertaken an investigation on the Fed’s bailout of the Bank of American-Merrill Lynch merger. “Specific documents subpoenaed include emails, notes of conversations and other documents,” his office noted.

“You look at the governing structure of the New York [Federal Reserve], it was run by the very banks that got the money,” said Eliot Spitzer told MSNBC’s Morning Meeting host Dylan Ratigan in late July. “This is a Ponzi scheme, an inside job. It is outrageous, it is time for Congress to say enough of this. And to give them more power now is crazy. The Fed needs to be examined carefully.”

Concluding his answer to the question of auditing the Federal Reserve, Rep. Frank told the Massachusetts audience: “The House will pass [H.R. 1207] probably in October.”

This video was uploaded to YouTube by user VegasBD on August 28, 2009.


Thursday, 27 August 2009

The Next Shoe to Drop in Banking: An Options Strategy

Reading - The Next Shoe to Drop in Banking: An Options Strategy http://tinyurl.com/ldr9u7

The financial sector of the U.S. economy has had nearly a year to address the problems that exacerbated the crisis last fall. But many observers think that the banks haven’t done enough, and that another round of trouble may be developing for the sector. I will outline some of those concerns and then suggest some ways to use options to profit if there is indeed another shoe to drop in banking.

The Thesis

The primary obstacle facing large banks is that they still carry most of the “toxic assets” that caused them so much trouble last year. As Elizabeth Warren explained recently, changes to accounting rules allowed banks to appear solvent only by allowing them to continue to obscure the market value of their troubled assets. By allowing banks to continue operating without any transparency or accountability, the federal government bought the banking industry some time, but did not address the fundamental problem. While some banks have begun quietly unloading some of their non-performing mortgages at steep discounts, they cannot do so in any real size without risking large write-downs that would spook equity holders.

A robust economic recovery – especially one in which new high-paying jobs are created and consumers regain their confidence – would lift the real estate market and boost the values of troubled assets. But while the administration and the banks have further leveraged themselves on the hope that such a recovery is forthcoming, there is little reason to expect a sustained rebound. Even if we do see improvements beyond the round of cost-cutting that enabled still-paltry, if positive second quarter earnings reports, such a recovery is likely to be a “jobless” one that will be insufficient to improve the fortunes of the major banks.

Two other catalysts to watch for include the commercial real estate (CRE) market and increased predatory activity on the part of banks themselves. The CRE story has been covered in great detail and has attracted widespread attention, mostly, I think, because it would amount to a new problem scenario in addition to all the familiar problems. The federal TALF program was extended by three to six months on August 17th and is intended to facilitate purchases of commercial mortgage-backed securities, but it is unclear whether government support will be sufficient to inspire continuing weak demand.

More alarming are the new products launched by major banks like Morgan Stanley (MS), JPMorgan Chase (JPM), Citigroup (C), and Wells Fargo (WFC). According to a recent story in BusinessWeek, these institutions are now getting into the sleazy payday loan business, are offering commercial loans linked to credit-default swaps (essentially increasing the financing burden on businesses precisely when they are least able to afford it), and are now approaching retail customers with structured notes – derivative instruments with complicated terms and opaque risks. Some or all of these might boost revenues at the banks over the short-term, while also entangling consumers and banks alike in a new round of ill-advised risk-taking.

In short, the fundamental picture for the major U.S. banks doesn’t look very different now than it did several months ago, especially once we discount the temporary effects of accounting changes and short-term stimulus packages. Bank stocks seem priced for a major economic recovery, but a quarter or two of continued weakness or negative surprises from the two other catalysts we mentioned could spark a substantial selloff in bank stocks.

The Trade

Options are a valuable tool for expressing views that can’t be stated in any other way. For simple buy/sell theses, buying or shorting a stock or ETF is sufficient. But in this case, we want to take a more nuanced position. It’s entirely possible, even if unlikely, that the U.S. economy will rebound strongly and bank stocks will rise amidst a new bull market. It’s also possible that no major surprises will emerge and the banks will be range-bound for months to come. So a straightforward put purchase isn’t the most desirable way to make this play.

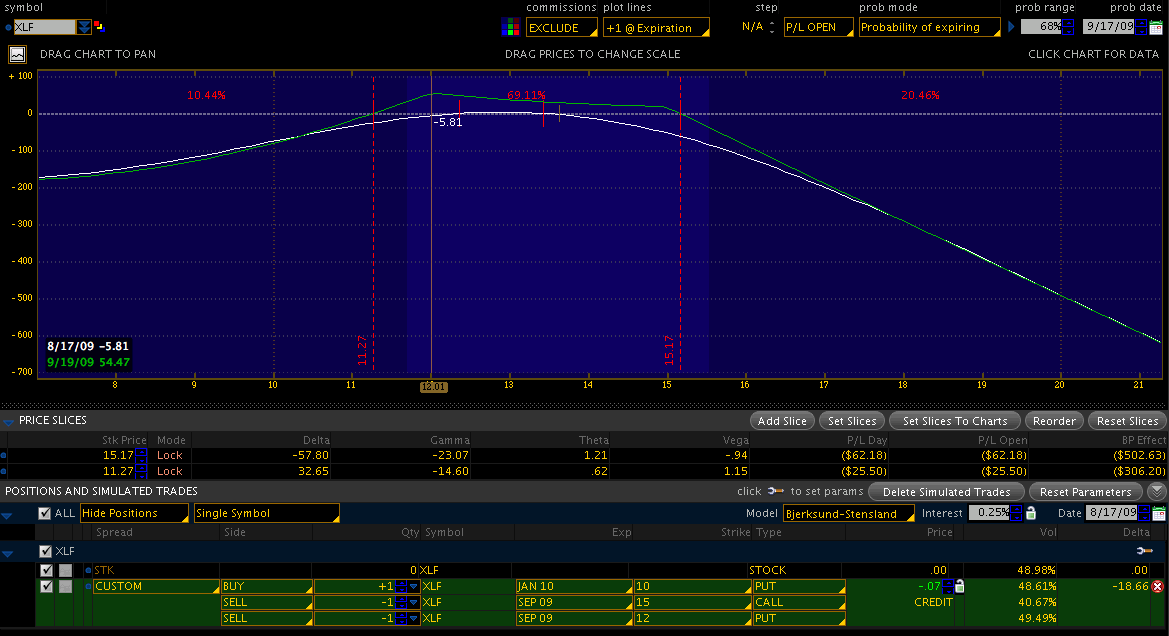
We want a position that is long vega – meaning that it will profit from an increase in implied volatility – since a decline in the financial sector is more likely than not to be a relatively sudden affair. We also want a position with some positive theta: since it may take some time for this pessimistic thesis to play out, we want to profit from time decay rather than let the value of our position trickle away. Finally, we want a position with some negative delta: we are bearish on the sector, after all.

click to enlarge

The XLF January 2010 10 puts could recently be bought for about $0.32; with -0.13 delta and 0.2 vega, these puts satisfy the first and third requirements. The XLF September 12 puts could recently be sold for about $0.20, and the September 15 calls could recently be sold for about $0.18. By selling this front-month strangle, we can bring in some income to help defray the cost of those back-month puts. The resulting three-legged position can be opened for a net credit of about $0.07; it will be profitable at September expiration if XLF is anywhere between roughly $11 and $15, with a maximum profit point near $12. At current levels of implied volatility, there is about a 70% chance that this position will be profitable at September expiration.

No trade is complete without a serious consideration of the risks involved. Because the front-month strangle we’re selling is only partially hedged (the long January put covers our short September put), it faces unlimited risk on the call side. As a result, it is advisable to hedge any upside breakout above $15 with either stock or long calls. We follow a version of this approach in our newsletter, and Condor Options' members have witnessed how helpful even a weekly rebalancing hedge can be.

Managing the trade after September expiry is relatively straightforward: as long as the underlying thesis of the trade is intact, we can sell short-term options against our core long position to generate income and reduce our cost basis. If the financial sector does begin to weaken, it will make sense to look further out of the money in order to allow more room for price declines.

Wednesday, 26 August 2009

Relief Rallies Are Never Made To Last

Reading - Relief Rallies Are Never Made To Last http://tinyurl.com/mdqp5g

In the relief rally much like the great depression long before, Big spike in NY state bankruptcies, healthcare reform will improve our quality of life, Government cannot create recovery and wealth, bureaucrats of the economy are working against the public, dollar rallies will be hailed as recovery, retail sales declining 21 percent at one place we know of, Madoff victims still battle for compensation,

Since March we have watched a stock market rally borne by low volume and short covering. The gains are reminiscent of the rallies of 1930 and 1932. What you are witnessing is a rally engineered by our government. If you watch the tape and you can read it you can see exactly what they are doing, and how they are doing it. Yes, it is legal under an Executive Order singed by President Ronald Reagan in the aftermath of the October 19th, 1997 collapse of the stock market. It was named the “Working Group on Financial Markets” and was to be used for such emergencies. Unfortunately, like many things in government, the mission of the “Plunge Protection Team” has been distorted. For over the last more than ten years it has been used to manipulate markets 24/7. Thus, what you are witnessing is a sucker rally, which has little hope of lasting.

What do you do with a market that has a trailing P/E of 24 times earnings? You stay as far away from it as possible.

Now that the stimulus has exhausted itself consumption is falling more rapidly, bills are being paid off and many have taken to saving again. If consumption cannot hold its own or increase during a large stimulus, when can it then? In other words how bad would the drop in GDP been if there had been no stimulus?

America is in a depression not a severe recession. If it were not, why would the Fed and our Treasury Department commit us for $23.7 trillion, and why would our entire financial industry have to be bailed out? Along with this fiat solution comes the political goals of corporatist fascism. Taken away have been the natural solution of growth within the private sector and the purging of excesses within the system. Those arguments are only heard on the Internet and talk radio. The people who our President wants to put on terrorist lists, or better yet has probably already put on terrorist lists, as you and me who speak up and demand our rights.

Our government for the past 20 years has been the most corrupt in American history. This is in your face corruption in banking, Wall Street, corporate America, in our congress and Senate and among our bureaucrats. Our legislation is written in secret by special interests and passed with very few even having read the legislation.

Then we have the change our President and his masters have planned for us. A health reform plan that rations healthcare, Health benefits and procedures will be made by bureaucrats. Everyone will carry a National Health Card ID that will contain your health records as well as federal access to very financial holdings. You will also get to subsidize union health plans and community organizer health plans, such as those of ACORN. Our new Government will be free of judicial review and price fixing. The government will set wages in the healthcare industry including those for doctors.

Insurance is mandatory and your employer will pay for it if he stays in business. Medicaid will be reduced as will services for the old and chronically ill. All doctors would be paid the same no matter what their specialty, training and experience. Hospital doctors will be penalized for what the government deems preventable re-admission. Government will prepare your taxes prior to death as they provide an approved list of end of life resources, to help guide you to your demise. If you do not take your own life government will arrange it for you. The list goes on and on. This is the same list used in Nazi Germany.

Government cannot create recovery and wealth. The insistence of the fed of massive injections of money and credit only eventually destroys wealth and capital. Such devices demand more taxes at a time when unemployment is rising, and tax revenues are falling; yet, debt is rising exponentially. We have a cadre of elitist banks, Wall Street firms, insurance companies and transnational corporations that will never be allowed to fail. Each time they use leverage and gamble and lose you will get to pay for it, on a never-ending basis. This is the heart of corporatist fascism. All those not in the elite Illuminist circle will eventually be gobbled up into giant transnational monopolies under world government.

Today’s modus operandi of the Treasury, the Fed, Congress, our President and the faceless bureaucrats from the Council on Foreign relations, Trilateral Commission and the Bilderberg Group is to debase our currency and other currencies as well and to increase unemployment, reduce income and stop capital formation. Whatever is left over will be confiscated from Americans, because the Illuminists believe that all your wealth belongs to them, because they allowed you to earn it. That is why they are chasing down all the offshore accounts. Once that is completed they will have a financial dossier first on Americans and then everyone in the world. Ultimately all countries will be currency blocked and then they will control all the world’s wealth. Of course, we now have to stop that. We’ll have to remove them from their pedestal. Egalitarianism caused 300,000 Illuminists to lose their heads in the late 1700s in France. History has a way of repeating itself.

The average person now pays about 40% in taxation, direct and indirect. If Health Care Reform and Cap & Trade are passed you can add another 40%. That is 80% Americans. This is exactly what the gang from the CFR has planned for you. That, of course, does not factor in inflation.

We are facing the worst depression in America’s history and perhaps in the last 500 years. Eventually due to higher taxes and less opportunities people will close up businesses and walk away from their jobs. These are the jobs that make the economy work.

How far away is collapse? We just do not know, but a good bet is within three years and perhaps a lot sooner. The trigger will probably be a collapsing dollar or a derivate collapse. Maybe it could be the passage of the HR 1270 to audit and investigate the Fed. When the public discovers what the Fed has been up to there will be thunder and lightning. Could it be that finally the public and professionals will demand front-running Goldman and 15 other Illuminist firms to return the money they have stolen? As you can see the media has buried the story. This gives you an idea of the shape of things to come. Get ready for hard times and protect your wealth in gold and silver related assets.

Many believe that global reflation and recovery chances are getting greater and that the American consumer is about to ride to the rescue. We do not know what US economy they are looking at, but it is not the same one we are. Unemployment continues to rise. Consumers are paying off debt and consumer buying continues to fall. What can they be missing here? The psychology of the public changed two years ago and it is still going in the same direction. Just because there is global reflation it doesn’t mean consumers will take the bait and buy. The Fed and many other central banks may be coordinating reflation but it doesn’t mean banks will lend and consumers will buy.

We hear a dollar rally will bring back American and world confidence. We just had a dollar rally to 89.5 and it evaporated. As we write it is 78.07 not only having great difficulty rallying back past 80, but government intervention had to save it last Friday as it tested the 77.50 area. At the same time budget deficits get larger and larger and the fed cannot print money and credit fast enough. Right now debt issuance is being secretly purchased by the Fed and all the central banks know it. These are not formulas for success, but for hyperinflation.

We ask over and over again how is it that the major policymakers and top economists at the BIS, Bank for International Settlements, the bankers bank, in Basel (Bale) Switzerland, said the US and world finance were headed for very serious trouble, but yet the BIS and the central banks rejected their admonitions? The reason is the bankers knew the US and world economies were being deliberately destroyed in order to force the world’s population to accept world government.

These economists and analysts have been proved correct but a power greater than the BIS was pulling the strings. Obviously having the biggest failure since 1930 doesn’t concern the BIS or its masters.

Fifty-five central banks own the BIS and every two months they journey to the Basel headquarters near the German border to discuss direction, drink the world’s best wines and to eat the best cuisine. Then there is the BIS’s privately owned country club and tennis accommodations. This is why the BIS is called the “Vatican of Finance.” All meetings are in secret and nothing is ever divulged. It is a stock cooperation and once was publicly traded until they forced sale of the shares owned by the public. Needless to say, they tried to screw the shareholders on the buyback.

The BIS pays no taxes and it’s members and employees enjoy extensive immunity. The BIS is totally a secret cabal of bankers. It manages 4% of the world’s currency reserves and 120 tons of gold. They set interest rates as well. What a sweet racket.

It should have been obvious to many economists that what Greenspan did during the 1990s creating the dot.com boom and then their real estate bubble that he was leading America toward financial trouble. The management of the BIS and those 55 central bankers had to know these were the wrong things to do, as the BIS professional staff was saying you are doing the wrong thing.

The BIS even published a report in 2003 warning buyers about collateralized debt obligations and the incestuous ratings of the rating services with Wall Street. The warnings were deliberately ignored. Since Ben Bernanke has taken over it’s been more of the same. Whatever they do it is over. We will have our deflationary depression and more war and the world public will stumble to their demise.

AMG data reports equity fund outflows were $1.1 billion for the week ended 8/19 versus inflows of $391 million the prior week.

July existing home sales were better, but this is the center of the home buying season, much Fed money has been poured into the economy including an $8,000 first time buyer tax credit. Single family homes sold fell 5,000 units, as Northeast condo sales rose.

The big problems are fewer and fewer qualified buyers and massive inventory, which grow every day, plus all the houses lenders haven’t even listed yet. First-time buyers and foreclosures, short sale buyers, the distressed investors, represent 61% of the estimated July sales. The $8,000 incentive is similar to the Cash for Clunkers. It just takes sales away from the future. The home selling season peaked this month. Then you have the foreclosure flippers, who if they cannot get a buyer have to rent the dwelling out. The problem is the rental market is loaded with inventory as well. The percentage of properties in foreclosure or delinquency has hit a high of 13.2% of all single-family mortgages. Making matters worse is that there has been a steady jump in foreclosures in prime mortgages and FHA insured mortgages most of which are the result of a resumption of subprime lending 1-1/2 years ago. The Fed trying to put a floor under the market will end up being a loser to be added to their long list of fascist policies.

continue reading- http://theinternationalforecaster.com/International_Forecaster_Weekly/Relief_Rallies_Are_Never_Made_To_Last