XIAM007

Making Unique Observations in a Very Cluttered World

Friday, 28 August 2009

Rep. Frank: House will pass Ron Paul’s ‘audit the Fed’ bill this year

Watching - VIDEO - c - http://bit.ly/ztw4P

Powerful House Financial Services Committee chairman says central bank’s lending powers to be ‘curtailed’

Congressman Barney Frank (D-MA), one of the most unabashed liberals in the U.S. House of Representatives, told a Massachusetts town hall recently that Texas Republican Congressman Ron Paul’s bill to audit the Federal Reserve bank will clear his chamber by October.

Over half of the House members, most of them Republican, have signed on to the bill, H.R. 1207.

Though Frank disagrees — as many proponents of the bill contend — that the Fed is the cause of the U.S. dollar’s shrinking value, he told a Massachusetts audience that he’s been a proponent of greater transparency at the nation’s central bank for some time.

“Here’s what we plan to do: I want to restrict the powers of the Federal Reserve in a number of ways,” he said. “First of all, they will be the major losers of power if we’re successful, as I believe we will be, setting up that, uh, financial product protection committee.”

The committee Frank mentioned was proposed by President Barack Obama during the campaign, as a way of protecting consumers. It was formally presented to Congress in the President’s financial regulatory reform white papers in July, noted law firm Wiley Rein LLP.

“The Federal Reserve is now charged with protecting consumers,” continued Frank. “They were supposed to do sub-prime mortgage restricted … Congress in 1994 gave the Federal Reserve the power to adopt rules to ban bad sub-prime mortgages. … They have the power to ban credit card abuses. They have the power to do most of it. They, under Greenspan, did nothing.

“Under Bernanke, they started to do things, but only after Congress started, when I became chairman of the [House Financial Services Committee], we began to act on these things: Sub-prime mortgages, credit cards, overdraft … And after we started, the Fed did. So, that’s why one of the reasons why in the new consumer protection agency we will take away from the Federal Reserve the power to do consumer protection.”

Frank added that Congress will reverse an action by the Democratic Congress of 1932 that gives the Fed authority to lend money at will.

“Under section 13.3 of the Federal Reserve Act, they can lend money to whoever they want,” he said. “We are going to curtail that lending power. We are going to put some constraints on it.”

He concluded: “Finally, we are going to subject them to a complete audit. I’ve been working with Ron Paul, the main sponsor of that bill …” Several in the audience applauded. “He believes that we don’t want to have the audit appear as if it is influencing monetary policy because that would be inflationary … One of the things that will show you is what the Federal Reserve buys and sells. That will be made public, but not instantly. If it were instant, you would have a lot of people trading off that and it would have too much impact on the market. Again, Ron agrees with that. So, we will probably have that data released after a time period of several months — enough time so it won’t be market sensitive.”

Danger in transparency?

The pervasive argument against transparency at the nation’s central banking institution was repeated by Treasury Secretary Tim Geithner during a recent dialog with popular social bookmarking Web site Digg.com.

Geithner said that he’s sure “people understand that you want to keep politics out of monetary policy,” adding that auditing the Fed is “a line that we do not want to cross” because of the possible danger to the U.S. economy.

The argument is strikingly similar to one posed by the Federal Reserve’s legal counsel ina Freedom of Information Act lawsuit filed by Bloomberg News in an attempt to force disclosure of the institutions that received billions in bailout money.

Loretta Preska, chief judge of the Manhattan U.S. District Court, ruled Monday that the Fed had “improperly withheld agency records” in response to the FOIA request, adding that the argument of danger to the economy was based merely on “conjecture” and not evidence.

“[The] risk of looking weak to competitors and shareholders is an inherent risk of market participation; information tending to increase that risk does not make the information privileged or confidential,” she wrote.

Opposition to Fed powers growing

Eliot Spitzer, the disgraced former Governor and Attorney General of New York — at one time known as the “sheriff” of Wall Street — has assaulted the bank bailouts as “America’s greatest theft and cover-up ever” and called the Federal Reserve bank a “Ponzi scheme” that must be held accountable for its actions.

Additionally, the House Domestic Policy Subcommittee plans to probe how the Troubled Asset Relief Program’s (TARP) funds were dispersed by the Fed. Expressing his frustration before the Government and Oversight Committee, Congressman Dennis Kucinich (D-OH) suggested that the Federal Reserve may be paying banks to hoard money and avoid making loans, instead of using the TARP funds to keep people in their homes.

To support his assertion, Kucinich cited a Bloomberg report which noted that “banks’ excess reserves at the Fed rose to a record $877.1 billion daily average in the two weeks ended May 20, from $2 billion a year earlier.

“Excess reserves — money available for lending that banks choose to leave with the Fed instead — averaged $743.9 billion in the first two weeks of this month,” the report continued.

“First, Congress was told that TARP was for the purchase of toxic assets, to help keep people in their homes,” the Congressman said. “Then the Bush Administration switched the program. Next, Congress was told that the TARP funds were instead needed to bail out the banks, in the form of a direct capital infusion, to keep credit markets alive.”

In a media advisory, Kucinich added: “If TARP isn’t about keeping people in their homes or providing credit to businesses, what is it for? I think the vast majority of Americans would be outraged to learn their tax dollars were facilitating hoarding at the Fed and increased profit making for banks.”

Kucinich’s Domestic Policy Subcommittee has also undertaken an investigation on the Fed’s bailout of the Bank of American-Merrill Lynch merger. “Specific documents subpoenaed include emails, notes of conversations and other documents,” his office noted.

“You look at the governing structure of the New York [Federal Reserve], it was run by the very banks that got the money,” said Eliot Spitzer told MSNBC’s Morning Meeting host Dylan Ratigan in late July. “This is a Ponzi scheme, an inside job. It is outrageous, it is time for Congress to say enough of this. And to give them more power now is crazy. The Fed needs to be examined carefully.”

Concluding his answer to the question of auditing the Federal Reserve, Rep. Frank told the Massachusetts audience: “The House will pass [H.R. 1207] probably in October.”

This video was uploaded to YouTube by user VegasBD on August 28, 2009.


Thursday, 27 August 2009

The Next Shoe to Drop in Banking: An Options Strategy

Reading - The Next Shoe to Drop in Banking: An Options Strategy http://tinyurl.com/ldr9u7

The financial sector of the U.S. economy has had nearly a year to address the problems that exacerbated the crisis last fall. But many observers think that the banks haven’t done enough, and that another round of trouble may be developing for the sector. I will outline some of those concerns and then suggest some ways to use options to profit if there is indeed another shoe to drop in banking.

The Thesis

The primary obstacle facing large banks is that they still carry most of the “toxic assets” that caused them so much trouble last year. As Elizabeth Warren explained recently, changes to accounting rules allowed banks to appear solvent only by allowing them to continue to obscure the market value of their troubled assets. By allowing banks to continue operating without any transparency or accountability, the federal government bought the banking industry some time, but did not address the fundamental problem. While some banks have begun quietly unloading some of their non-performing mortgages at steep discounts, they cannot do so in any real size without risking large write-downs that would spook equity holders.

A robust economic recovery – especially one in which new high-paying jobs are created and consumers regain their confidence – would lift the real estate market and boost the values of troubled assets. But while the administration and the banks have further leveraged themselves on the hope that such a recovery is forthcoming, there is little reason to expect a sustained rebound. Even if we do see improvements beyond the round of cost-cutting that enabled still-paltry, if positive second quarter earnings reports, such a recovery is likely to be a “jobless” one that will be insufficient to improve the fortunes of the major banks.

Two other catalysts to watch for include the commercial real estate (CRE) market and increased predatory activity on the part of banks themselves. The CRE story has been covered in great detail and has attracted widespread attention, mostly, I think, because it would amount to a new problem scenario in addition to all the familiar problems. The federal TALF program was extended by three to six months on August 17th and is intended to facilitate purchases of commercial mortgage-backed securities, but it is unclear whether government support will be sufficient to inspire continuing weak demand.

More alarming are the new products launched by major banks like Morgan Stanley (MS), JPMorgan Chase (JPM), Citigroup (C), and Wells Fargo (WFC). According to a recent story in BusinessWeek, these institutions are now getting into the sleazy payday loan business, are offering commercial loans linked to credit-default swaps (essentially increasing the financing burden on businesses precisely when they are least able to afford it), and are now approaching retail customers with structured notes – derivative instruments with complicated terms and opaque risks. Some or all of these might boost revenues at the banks over the short-term, while also entangling consumers and banks alike in a new round of ill-advised risk-taking.

In short, the fundamental picture for the major U.S. banks doesn’t look very different now than it did several months ago, especially once we discount the temporary effects of accounting changes and short-term stimulus packages. Bank stocks seem priced for a major economic recovery, but a quarter or two of continued weakness or negative surprises from the two other catalysts we mentioned could spark a substantial selloff in bank stocks.

The Trade

Options are a valuable tool for expressing views that can’t be stated in any other way. For simple buy/sell theses, buying or shorting a stock or ETF is sufficient. But in this case, we want to take a more nuanced position. It’s entirely possible, even if unlikely, that the U.S. economy will rebound strongly and bank stocks will rise amidst a new bull market. It’s also possible that no major surprises will emerge and the banks will be range-bound for months to come. So a straightforward put purchase isn’t the most desirable way to make this play.

We want a position that is long vega – meaning that it will profit from an increase in implied volatility – since a decline in the financial sector is more likely than not to be a relatively sudden affair. We also want a position with some positive theta: since it may take some time for this pessimistic thesis to play out, we want to profit from time decay rather than let the value of our position trickle away. Finally, we want a position with some negative delta: we are bearish on the sector, after all.

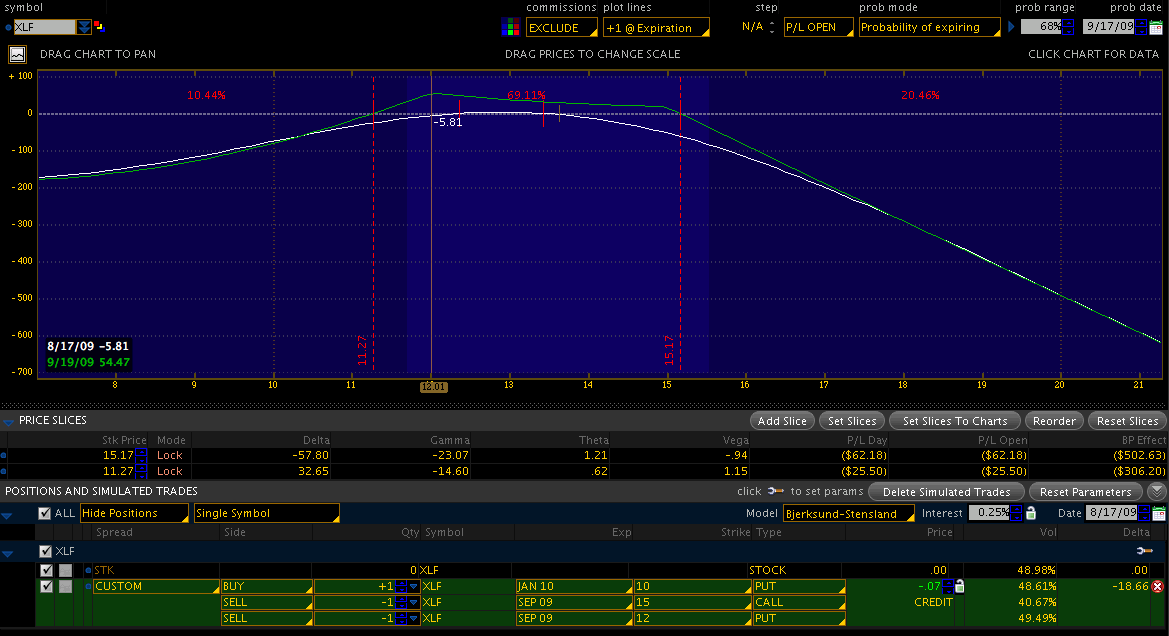
click to enlarge

The XLF January 2010 10 puts could recently be bought for about $0.32; with -0.13 delta and 0.2 vega, these puts satisfy the first and third requirements. The XLF September 12 puts could recently be sold for about $0.20, and the September 15 calls could recently be sold for about $0.18. By selling this front-month strangle, we can bring in some income to help defray the cost of those back-month puts. The resulting three-legged position can be opened for a net credit of about $0.07; it will be profitable at September expiration if XLF is anywhere between roughly $11 and $15, with a maximum profit point near $12. At current levels of implied volatility, there is about a 70% chance that this position will be profitable at September expiration.

No trade is complete without a serious consideration of the risks involved. Because the front-month strangle we’re selling is only partially hedged (the long January put covers our short September put), it faces unlimited risk on the call side. As a result, it is advisable to hedge any upside breakout above $15 with either stock or long calls. We follow a version of this approach in our newsletter, and Condor Options' members have witnessed how helpful even a weekly rebalancing hedge can be.

Managing the trade after September expiry is relatively straightforward: as long as the underlying thesis of the trade is intact, we can sell short-term options against our core long position to generate income and reduce our cost basis. If the financial sector does begin to weaken, it will make sense to look further out of the money in order to allow more room for price declines.

Wednesday, 26 August 2009

Relief Rallies Are Never Made To Last

Reading - Relief Rallies Are Never Made To Last http://tinyurl.com/mdqp5g

In the relief rally much like the great depression long before, Big spike in NY state bankruptcies, healthcare reform will improve our quality of life, Government cannot create recovery and wealth, bureaucrats of the economy are working against the public, dollar rallies will be hailed as recovery, retail sales declining 21 percent at one place we know of, Madoff victims still battle for compensation,

Since March we have watched a stock market rally borne by low volume and short covering. The gains are reminiscent of the rallies of 1930 and 1932. What you are witnessing is a rally engineered by our government. If you watch the tape and you can read it you can see exactly what they are doing, and how they are doing it. Yes, it is legal under an Executive Order singed by President Ronald Reagan in the aftermath of the October 19th, 1997 collapse of the stock market. It was named the “Working Group on Financial Markets” and was to be used for such emergencies. Unfortunately, like many things in government, the mission of the “Plunge Protection Team” has been distorted. For over the last more than ten years it has been used to manipulate markets 24/7. Thus, what you are witnessing is a sucker rally, which has little hope of lasting.

What do you do with a market that has a trailing P/E of 24 times earnings? You stay as far away from it as possible.

Now that the stimulus has exhausted itself consumption is falling more rapidly, bills are being paid off and many have taken to saving again. If consumption cannot hold its own or increase during a large stimulus, when can it then? In other words how bad would the drop in GDP been if there had been no stimulus?

America is in a depression not a severe recession. If it were not, why would the Fed and our Treasury Department commit us for $23.7 trillion, and why would our entire financial industry have to be bailed out? Along with this fiat solution comes the political goals of corporatist fascism. Taken away have been the natural solution of growth within the private sector and the purging of excesses within the system. Those arguments are only heard on the Internet and talk radio. The people who our President wants to put on terrorist lists, or better yet has probably already put on terrorist lists, as you and me who speak up and demand our rights.

Our government for the past 20 years has been the most corrupt in American history. This is in your face corruption in banking, Wall Street, corporate America, in our congress and Senate and among our bureaucrats. Our legislation is written in secret by special interests and passed with very few even having read the legislation.

Then we have the change our President and his masters have planned for us. A health reform plan that rations healthcare, Health benefits and procedures will be made by bureaucrats. Everyone will carry a National Health Card ID that will contain your health records as well as federal access to very financial holdings. You will also get to subsidize union health plans and community organizer health plans, such as those of ACORN. Our new Government will be free of judicial review and price fixing. The government will set wages in the healthcare industry including those for doctors.

Insurance is mandatory and your employer will pay for it if he stays in business. Medicaid will be reduced as will services for the old and chronically ill. All doctors would be paid the same no matter what their specialty, training and experience. Hospital doctors will be penalized for what the government deems preventable re-admission. Government will prepare your taxes prior to death as they provide an approved list of end of life resources, to help guide you to your demise. If you do not take your own life government will arrange it for you. The list goes on and on. This is the same list used in Nazi Germany.

Government cannot create recovery and wealth. The insistence of the fed of massive injections of money and credit only eventually destroys wealth and capital. Such devices demand more taxes at a time when unemployment is rising, and tax revenues are falling; yet, debt is rising exponentially. We have a cadre of elitist banks, Wall Street firms, insurance companies and transnational corporations that will never be allowed to fail. Each time they use leverage and gamble and lose you will get to pay for it, on a never-ending basis. This is the heart of corporatist fascism. All those not in the elite Illuminist circle will eventually be gobbled up into giant transnational monopolies under world government.

Today’s modus operandi of the Treasury, the Fed, Congress, our President and the faceless bureaucrats from the Council on Foreign relations, Trilateral Commission and the Bilderberg Group is to debase our currency and other currencies as well and to increase unemployment, reduce income and stop capital formation. Whatever is left over will be confiscated from Americans, because the Illuminists believe that all your wealth belongs to them, because they allowed you to earn it. That is why they are chasing down all the offshore accounts. Once that is completed they will have a financial dossier first on Americans and then everyone in the world. Ultimately all countries will be currency blocked and then they will control all the world’s wealth. Of course, we now have to stop that. We’ll have to remove them from their pedestal. Egalitarianism caused 300,000 Illuminists to lose their heads in the late 1700s in France. History has a way of repeating itself.

The average person now pays about 40% in taxation, direct and indirect. If Health Care Reform and Cap & Trade are passed you can add another 40%. That is 80% Americans. This is exactly what the gang from the CFR has planned for you. That, of course, does not factor in inflation.

We are facing the worst depression in America’s history and perhaps in the last 500 years. Eventually due to higher taxes and less opportunities people will close up businesses and walk away from their jobs. These are the jobs that make the economy work.

How far away is collapse? We just do not know, but a good bet is within three years and perhaps a lot sooner. The trigger will probably be a collapsing dollar or a derivate collapse. Maybe it could be the passage of the HR 1270 to audit and investigate the Fed. When the public discovers what the Fed has been up to there will be thunder and lightning. Could it be that finally the public and professionals will demand front-running Goldman and 15 other Illuminist firms to return the money they have stolen? As you can see the media has buried the story. This gives you an idea of the shape of things to come. Get ready for hard times and protect your wealth in gold and silver related assets.

Many believe that global reflation and recovery chances are getting greater and that the American consumer is about to ride to the rescue. We do not know what US economy they are looking at, but it is not the same one we are. Unemployment continues to rise. Consumers are paying off debt and consumer buying continues to fall. What can they be missing here? The psychology of the public changed two years ago and it is still going in the same direction. Just because there is global reflation it doesn’t mean consumers will take the bait and buy. The Fed and many other central banks may be coordinating reflation but it doesn’t mean banks will lend and consumers will buy.

We hear a dollar rally will bring back American and world confidence. We just had a dollar rally to 89.5 and it evaporated. As we write it is 78.07 not only having great difficulty rallying back past 80, but government intervention had to save it last Friday as it tested the 77.50 area. At the same time budget deficits get larger and larger and the fed cannot print money and credit fast enough. Right now debt issuance is being secretly purchased by the Fed and all the central banks know it. These are not formulas for success, but for hyperinflation.

We ask over and over again how is it that the major policymakers and top economists at the BIS, Bank for International Settlements, the bankers bank, in Basel (Bale) Switzerland, said the US and world finance were headed for very serious trouble, but yet the BIS and the central banks rejected their admonitions? The reason is the bankers knew the US and world economies were being deliberately destroyed in order to force the world’s population to accept world government.

These economists and analysts have been proved correct but a power greater than the BIS was pulling the strings. Obviously having the biggest failure since 1930 doesn’t concern the BIS or its masters.

Fifty-five central banks own the BIS and every two months they journey to the Basel headquarters near the German border to discuss direction, drink the world’s best wines and to eat the best cuisine. Then there is the BIS’s privately owned country club and tennis accommodations. This is why the BIS is called the “Vatican of Finance.” All meetings are in secret and nothing is ever divulged. It is a stock cooperation and once was publicly traded until they forced sale of the shares owned by the public. Needless to say, they tried to screw the shareholders on the buyback.

The BIS pays no taxes and it’s members and employees enjoy extensive immunity. The BIS is totally a secret cabal of bankers. It manages 4% of the world’s currency reserves and 120 tons of gold. They set interest rates as well. What a sweet racket.

It should have been obvious to many economists that what Greenspan did during the 1990s creating the dot.com boom and then their real estate bubble that he was leading America toward financial trouble. The management of the BIS and those 55 central bankers had to know these were the wrong things to do, as the BIS professional staff was saying you are doing the wrong thing.

The BIS even published a report in 2003 warning buyers about collateralized debt obligations and the incestuous ratings of the rating services with Wall Street. The warnings were deliberately ignored. Since Ben Bernanke has taken over it’s been more of the same. Whatever they do it is over. We will have our deflationary depression and more war and the world public will stumble to their demise.

AMG data reports equity fund outflows were $1.1 billion for the week ended 8/19 versus inflows of $391 million the prior week.

July existing home sales were better, but this is the center of the home buying season, much Fed money has been poured into the economy including an $8,000 first time buyer tax credit. Single family homes sold fell 5,000 units, as Northeast condo sales rose.

The big problems are fewer and fewer qualified buyers and massive inventory, which grow every day, plus all the houses lenders haven’t even listed yet. First-time buyers and foreclosures, short sale buyers, the distressed investors, represent 61% of the estimated July sales. The $8,000 incentive is similar to the Cash for Clunkers. It just takes sales away from the future. The home selling season peaked this month. Then you have the foreclosure flippers, who if they cannot get a buyer have to rent the dwelling out. The problem is the rental market is loaded with inventory as well. The percentage of properties in foreclosure or delinquency has hit a high of 13.2% of all single-family mortgages. Making matters worse is that there has been a steady jump in foreclosures in prime mortgages and FHA insured mortgages most of which are the result of a resumption of subprime lending 1-1/2 years ago. The Fed trying to put a floor under the market will end up being a loser to be added to their long list of fascist policies.

continue reading- http://theinternationalforecaster.com/International_Forecaster_Weekly/Relief_Rallies_Are_Never_Made_To_Last

FDIC Sets Rules for Private Equity to Buy Shut Banks

Reading - FDIC Sets Rules for Private Equity to Buy Shut Banks http://bit.ly/DcF9Z

The Federal Deposit Insurance Corp. approved weakened rules for letting private-equity firms buy failed banks, aiming to widen a pool of potential acquirers for a growing roster of shuttered lenders.

The FDIC board, in a 4-1 vote today, lowered Tier 1 capital ratio requirements for private-equity buyers to 10 percent from the 15 percent proposed July 2. Investors will be required to maintain the 10 percent ratio for at least three years.

“The FDIC recognizes the need for additional capital in the banking system,” FDIC Chairman Sheila Bair said at the meeting in Washington. “We want to maximize investor interest in failed institutions.”

The regulator is seeking to lure non-bank investors including private-equity firms to bid on assets of collapsed banks as failures reach a 17-year high with 81 so far in 2009. The surge, which has drained the FDIC’s insurance fund by more than $21 billion, has forced the agency to enter loss-sharing arrangements and absorb other costs.

The FDIC has twice brokered deals with private-equity groups this year. In March, California-based IndyMac Federal Bank, split off from IndyMac Bancorp Inc., was sold to investors led by Steven Mnuchin, an ex-Goldman Sachs Group Inc. investment banker, and including buyout firm J.C. Flowers & Co. Florida’s BankUnited Financial Corp. was sold in May to firms including Blackstone Group and Wilbur Ross’s WL Ross & Co.

Today’s vote, which followed a public comment period on the July proposal, shows the FDIC was listening to critics who said the initial plan would drive away potential investors, Ross said in a Bloomberg Television interview.

‘Champagne-Cork Popper’

“The new proposal is better than the one they had before but it isn’t a champagne-cork popper,” Ross said.

The agency agreed to shelve a proposal that would have required investors that owned at least two banks to cover losses in the event of a failure. The rules scale back this provision, applying it only if a group of investors owns at least 80 percent of two or more banks.

Office of Thrift Supervision Acting Director John Bowman, the only FDIC board member to vote against new rules, said there isn’t sufficient evidence that the guidelines are needed.

“It is hard to know whether the requirements are justified,” Bowman said. “The scope of the policy statement is overly broad and imprecise.”

U.S. Senator Jack Reed, a Rhode Island Democrat who leads a Banking Committee panel overseeing the securities industry, wrote to Bair in May asking her to spell out rules for private- equity firms investing in banks.

Saturday, 22 August 2009

Blackwater's Unwritten Death Contract

Reading - Blackwater's Unwritten Death Contract -http://bit.ly/3vKPia

Hats off to Mark Mazzetti of the New York Times for ferreting out what it was that sent CIA Director Leon Panetta scurrying over to Congress in late June.

According to Mazzetti, Panetta's top lieutenants, many of them holdovers from the last administration, had just told him that, under President Bush, they had farmed out assassinations to their Blackwater subsidiary. I use "they" advisedly, since the CIA holdovers that had kept Panetta in the dark continue to function as Panetta's top managers.

Panetta abruptly stopped the project and contritely briefed the intelligence committees. Until now, it was not clear what had prompted Panetta to set up hurried consultations with the intelligence "oversight" committees of the House and Senate.

An odd odor still hangs over the affair. After being briefed by Panetta, one committee member described him as "stunned" that his lingering lieutenants had kept information on the program from him until nearly five months into his tenure. Yet there is not the faintest hint that anyone on either committee dared to ask why Panetta continues to leave such tainted officials in very senior positions.

Anyone know why he does not send them packing?

Mazzetti quotes officials as admitting that "the C.I.A. did not have a formal contract with Blackwater" for a program with "lethal" authority. Putting out contracts on other people, I suppose you might call it, without a contract. http://www.nytimes.com/2009/08/20/us/20intel.html?_r=2

What Mazzetti does not mention -- and what he, like the vast majority of Americans, may not know -- is that there is a one-sentence umbrella "contract" available for use as authorization for such activities. It creates a structural fault, so to speak, and a legal loophole through which Bush and Cheney drove a Mack truck of lawlessness.

Useful Ambiguity

Bush administration lawyers were not the first to read considerable leeway into that loophole created by just one sentence in the language of the National Security Act of 1947. The sentence can be (ab)used as authorization for all manner of crime -- irrespective of existing law or executive order.

A Cheney-esque "unitary executive" perspective and a dismissive attitude toward lawmakers reinforced the Bush team's predilection to exploit the ambiguous language, taking it further than it had ever been taken in the past.

The Act (as slightly amended) stipulates that the CIA Director shall:

"Perform such functions and duties related to intelligence affecting the national security as the President or the National Security Council may from time to time direct."

There's the "umbrella contract." While more than one past President (I served under seven during my tenure at CIA) has taken advantage of that open language, the Bush administration translated the dodging into a new art form. This, in turn, was sustained by Frankenstein cottage industries like Blackwater to launch and operate the administration's own Gestapo. I use the word advisedly; do not blanch before it.

As for outsourcing, it is nothing new. The earlier Nazi Gestapo enjoyed umbrella authorization from the Fuhrer; they and the SS knew what was wanted, and famously "followed orders." There was absolutely no need to go back to supreme authority for approval to contract out some of their work. And German legislators turned out to be even more intimidated than ours -- if you can imagine it.

Charlatans Can Apply...and Some Stay On

As for an American President's freedom of action, all a President need do is surround himself with eager co-conspirators like the sycophant former Director of Central Intelligence, George Tenet (not to mention his, and Panetta's, lingering lieutenants), who give allegiance to their secret world of unchecked power, rather than to the Constitution of the United States. True, a Vice President thoroughly versed in using the levers of power also can be a valuable asset.

But the sine quo non for successful subversion of our Constitutional process is this: cowardly members of Congress so afraid of being painted pastel on terrorism that they abdicate their oversight responsibility. George W. Bush and Dick Cheney may have "misunderestimated" some things, but not Congress. They held it in scorn and contempt, and the Congress' behavior gave them every reason to believe they were right.

The Bush White House gave very high priority to "terrorification" of Congress and it paid off handsomely. The most senior congressional leaders caved, winking even at torture, kidnapping, warrantless eavesdropping, etc., etc., etc.

And on the subject of contracting, Congress' oversight role was, in a real sense, "contracted out" -- to eight invertebrate leaders from the House and Senate. Their see-no-evil acquiescence in whatever Bush and Cheney painted as a weapon in the so-called "war on terror" was driven solely by the lawmakers' felt need to appear tough on terrorism.

"After 9/11 everything changed," is certainly an overused aphorism. But it does apply to what happened to the spirit and soul of our country after President Bush was given the pulpit at the National Cathedral. Vengeance is ours, said the President. And the vast majority of Christian leaders were cowed into razoring out of their Bibles "Blessed are the Peacemakers."

Clergy and Congress clapped, and so did the Fawning Corporate Media (FCM). Don't you remember?

The situation bears striking resemblance to that described by German writer Sebastian Haffner, who was in Berlin in 1933 after the Reichstag fire (Germany's 9/11):

"What was missing is what in animals is called ‘breeding.' This is a solid inner kernel that cannot be shaken by external pressures, something noble and steely, a reserve of pride, principle, and dignity to be drawn on in the hour of trial. It is missing in Germans. "As a nation they are without backbone. That was shown in March 1933. At the moment of truth, when other nations rise spontaneously to the occasion, the Germans collectively and limply collapsed, yielded to a nervous breakdown, and became a nightmare to the rest of the world." ("Defying Hitler," p. 135)

Congress' Stormy Applause...

And our Congress? During the President's infamous State-of-the-Union address on Jan. 28, 2003 (yes, the one with the uranium-from-Africa-to-Iraq and other make-believe), Bush got the most unbridled applause when, after bragging about the 3,000 "suspected terrorists" whom he said had been arrested, he added:

"And many others have met a different fate. Let's put it this way: They are no longer a problem to the United States and our friends and allies."

The lawmakers' reaction and the cheering that followed in the FCM reminded me of the short italicized note that Pravda regularly tacked onto the bottom of paragraphs recording similarly fulsome leadership speeches: Burniye aplodismenty; vce stoyat! - Stormy applause; all rise! Even so, Soviet leaders generally avoided (as not quite presidential) seeking applause for thinly veiled allusions to extrajudicial killing.

...and Fawning Over Creeps

It is Congress that is collectively responsible for abdicating its oversight responsibility, while cheering creeps like Cofer Black, CIA's top counter-terrorism official from 1999 to May 2002 and now one of Blackwater's senior leaders.

On Sept. 26, 2002 in his prepared testimony to the Joint Congressional Inquiry on 9/11, the swashbuckling Black said this about "operational flexibility":

"All I want to say is that there was ‘before' 9/11 and ‘after' 9/11. After 9/11 the gloves came off. ... I know that we are on the right track today and as a result we are safer as a nation. ‘No Limits' aggressive, relentless, worldwide pursuit of any terrorist who threatens us is the only way to go and is the bottom line."

What were those "gloves" to which you referred, Mr. Black? Do you mean that legal restrictions were gone? And "No Limits?" Is it the case that there now are no limitations on your pursuit of terrorists? Whence do you derive that kind of authority, Mr. Black? These are just some of the pertinent questions that members of the congressional panel apparently felt would be impertinent to ask.

And authorization? In the Bush/Cheney White House, all it took was a presidential signature, like the one appearing in broad strokes of felt-tipped pen under the two-page executive memorandum of Feb. 7, 2002. http://www.gwu.edu/~nsarchiv/NSAEBB/NSAEBB127/02.02.07.pdf )

Last December the Senate Armed Forces Committee, without dissent, concluded that this memo, "opened the door" to abuse by exempting al Qaeda and Taliban detainees from Geneva protections. Alberto Gonzales, in a felicitous but inadvertent blunder, released that memo five years ago. It is a smoking gun. Someone, please, tell the FCM.

As for assassinations, the special presidential memoranda (often referred to as "Findings") that authorized covert action like the lethal activities of the CIA and Blackwater have not yet surfaced. They will, in due course, if the patriotic truth tellers who have now discussed assassination with the Times and Washington Post continue to put the Constitution and courage above secrecy oaths. Such oaths are aimed at protecting secrets, not crimes.

Vengeance is Ours

CIA operative Gary Schroen has told National Public Radio that, just days after 9/11, Cofer Black sent him to Afghanistan with orders to "Capture bin Laden, kill him, and bring his head back in a box on dry ice." As for other al Qaeda leaders, Black reportedly said, "I want their heads up on pikes."

Schroen told NPR he had been stunned that, for the first time in 30 years of service, he had received orders to kill targets rather than to capture them. Contacted by the radio network, Black would not confirm the exact words of the order to Schroen, but did not dispute Schroen's account.

This quaint tone reverberated among macho, Bush-friendly pundits in the FCM. Washington Post veteran Jim Hoagland, for example, published an open letter to President Bush on Oct. 31, 2001. It was no Halloween prank.

In his letter, Hoagland strongly endorsed what he termed the "wish" for "Osama bin Laden's head on a pike," an objective he attributed to Bush's "generals and diplomats." The consummate insider, Hoagland then virtually gave the real neoconservative game plan away by giving Bush the following ordering of priorities:

"The need to deal with Iraq's continuing accumulation of biological and chemical weapons and the technology to build a nuclear bomb can in no way be lessened by the demands of the Afghan campaign. You must conduct that campaign so that you can pivot quickly from it to end the threat Saddam Hussein's regime poses."

I have the feeling we are in for many more chapters recording how the lawlessness and savagery of post-9/11 Washington played out during the last seven years of the Bush/Cheney administration.

Ray McGovern works with Tell the Word, the publishing arm of the ecumenical Church of the Saviour in inner-city Washington. He was a CIA analyst for 27 years and now serves on the Steering Group of Veteran Intelligence Professionals for Sanity (VIPS).

This article appeared first on Consortiumnews.com.

No USA buyers? = U.S. Helps Spanish Company to Buy Texas Bank

Reading - No USA buyers? = U.S. Helps Spanish Company to Buy Texas Bank http://tinyurl.com/l8opra

Guaranty Bank, a deeply troubled Texas lender, was sold on Friday to Banco Bilbao Vizcaya Argentaria of Spain in one of the largest government-assisted deals offered to a foreign firm.

The federal government agreed to absorb most of the losses on $11 billion of Guaranty Bank assets in the sale agreement.

Federal regulators seized Guaranty Bank and simultaneously brokered the sale of its branches as well as most of the deposits and assets to BBVA Compass, the Spanish bank’s American subsidiary. The government, however, agreed to absorb most of the losses on $9.7 billion, or more than 80 percent, of the Guaranty assets included in the deal.

The failure is the fourth-largest since the financial crisis began, and the Federal Deposit Insurance Corporation projects that it will cost its deposit insurance fund about $3 billion.

Regulators also arranged for the sales of three smaller banks in Alabama and Georgia on Friday, bringing the total number of bank failures so far this year to 81. That compares with only 25 bank failures in all of 2008.

News that BBVA had submitted the winning bid leaked out earlier this week, but regulators waited until late Friday to orchestrate the takeover. That may be another sign that confidence in the financial system is being restored, since in contrast to past leaks, regulators did not immediately seize the bank over fears of rumors stoking a bank run.

Stockholders in Guaranty Bank will be wiped out, but the deal ensures that its depositors will not suffer losses. Although BBVA did not take control of the failed bank’s $344 million of brokered deposits, the F.D.I.C. said that it would reimburse brokers directly for those funds.

The government also agreed to shoulder the bulk of the losses on all of Guaranty’s loans — a deal sweetener that the government has rarely extended to overseas buyers.

BBVA agreed to buy $12 billion of the $13 billion assets left at Guaranty Bank, which it will ultimately sell to private investors. The F.D.I.C. agreed to take on the remaining $1 billion of assets, as well as cover losses on the $9.7 billion pool of risky loans that BBVA bought. The agreement calls for the government to take on about 80 percent of the first $2.3 billion of losses, and 95 percent of the losses above that threshold.

Loss-sharing agreements have become a standard part of the F.D.I.C.’s toolkit for resolving troubled banks, but rarely have they covered such a big portion of a failed bank’s assets.

And seldom are they offered to foreign buyers. Indeed, it appears the last time that an overseas bank received federal assistance in a failed bank deal was when the Bank of Ireland scooped up four New Hampshire banks in September 1991.

Analysts say the BBVA deal may signal that the F.D.I.C. will be more open to bids from foreign banks. Many of the strongest American banks are occupied with deals they did last fall, while private equity firms have struggled to meet the high bar set by regulators. Weaker banks, meanwhile, have been hamstrung by their own losses. That has left regulators scrambling to drum up buyers.

José Maria Garcia Meyer, the head of BBVA’s American operations, said in a statement that the deal provided convincing evidence of the bank’s strength and stability during the current crisis. “This transaction further demonstrates BBVA’s clear commitment in building its U.S. franchise,” he added.

Along with its Spanish rival Banco Santander, BBVA has been ramping up its business in fast-growing American markets that have strong ties to Latin America. It made a series of expensive acquisitions in Texas over the last few years.

Guaranty, which is based in Austin, will add another 103 locations in Texas and 59 branches in California, where BBVA has been trying to establish a beachhead. That will give it a total of 767 locations in seven Sun Belt states and make it the nation’s 15th-largest commercial bank with about $49 billion in deposits.

Thursday, 20 August 2009

More Banks to Fail, and That's Good

Reading - More Banks to Fail, and That's Good -http://www.cnbc.com/id/3248...

U.S. banks will continue to fail at a steady rate over the next two years, and that's not necessarily a bad thing, former FDIC Chairman Bill Isaac told CNBC.

Isaac, who presided over one of the most tumultuous periods in banking history during the savings and loan crisis of the 1980s, said there remains a large amount of contagion in the system that needs to be removed.

"It's cleanup time," he said during a live interview. "For the next couple of years we will continue to have a steady flow of banking failures. I'm not expecting anything we can't handle or extraordinary in terms of size, but we will see a steady diet of bank failures over the next two years."

Bank failures have come amid a lack of liquidity that began with the collapse of the subprime mortgage business.

Five banks have failed in the past week, bringing the 2009 total to 77, according to the FDIC. The number pales to the situation during the S&L crisis, when the nation lost 3,000 institutions.

Click here for video of Isaac's full comments
"The (dollar) numbers are bigger today because everything's bigger today," Isaac said. "I don't think the failures are any larger today proportionate to the economy."


RELATED LINKS
Banks Will Lag Economic RecoveryBank Bailout Cash Cut
In fact, he said getting banks to the point where they are seized by the FDIC is a critical step to making sure the system functions properly.

"I would say the bank failures are not necessarily a bad thing,"" Isaac said. "When a bank fails we've got a deeply troubled institution that cannot lend money. If we go in and resolve the failure, the cleanup of that situation ... will enable the institution to get on with lending. The FDIC cleans out the problem loans. So it really does cleanse the system and help us get lending started again, which is what we need."